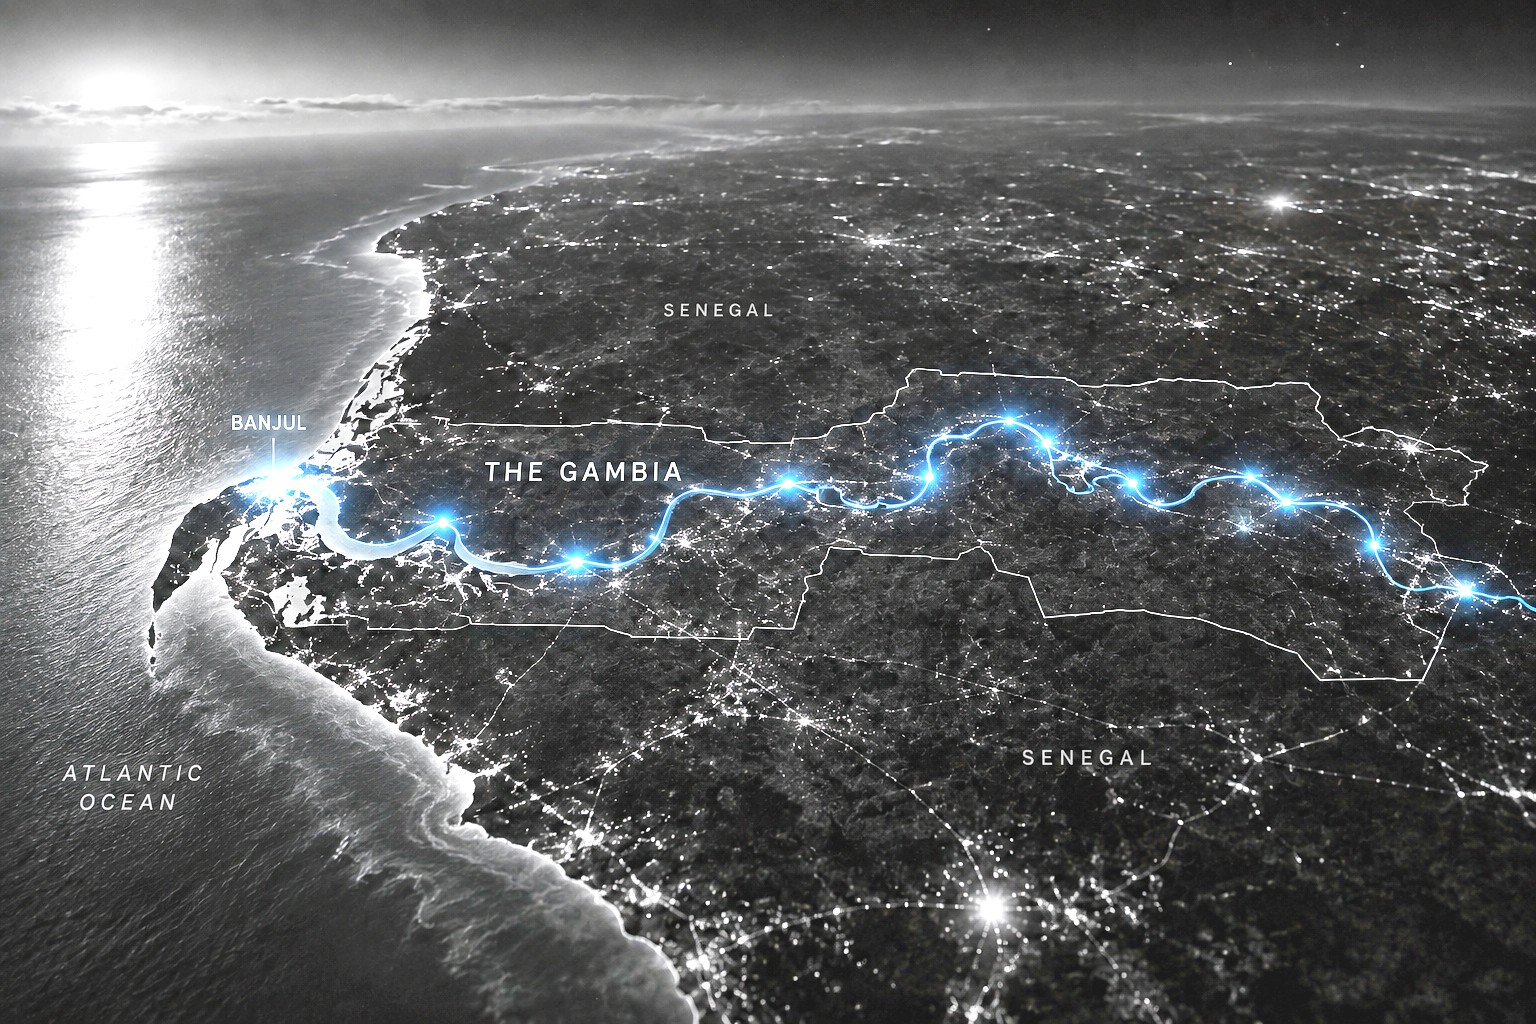
One of Africa’s smallest economies is undergoing a remarkably rapid financial transformation. Mobile money and fintech usage are expanding across The Gambia while the country builds the infrastructure needed to connect banks, digital wallets and fintech platforms into a more integrated national payment system.
BANJUL — September 17, 2026
The latest figures from the Central Bank of The Gambia show that fintech and mobile-money services continued expanding during the second quarter of 2026.
Cash-in transactions increased 4.4 per cent from the previous quarter to D28.2 billion, while cash-out transactions rose 5.3 per cent to D32.1 billion.
Behind those numbers is a much larger structural change.
From 19 to 82 per cent
The country’s formal financial inclusion rate increased from just 19 per cent in 2019 to 82 per cent in 2025, according to the FinScope Consumer Survey.
Financial exclusion simultaneously fell from 69 per cent to 14 per cent.
Mobile money has been one of the principal drivers of that transformation, alongside fintech companies, banks, microfinance institutions and credit unions.
For an economy where conventional banking infrastructure has historically been limited, the implications are considerable.
People do not necessarily have to wait for a bank branch to arrive.
The financial relationship can arrive digitally.
Building the rails underneath
The next challenge is making those different financial services work together.
The Gambia launched BANTABA 2.0 in December 2025, creating a national real-time interoperable payment platform designed to connect banks, mobile-money operators, fintech companies and public institutions.
The system uses Mojaloop technology and allows money to move between participating providers rather than remaining trapped inside separate financial networks.
The central bank is now reviewing its wider national payment strategy as digital merchant payments and government services expand.
A small economy can move quickly
The Gambia demonstrates something important about fintech in emerging markets.
Financial transformation does not necessarily begin with large banks building more branches.
It can begin with a mobile wallet.
Once people can receive money digitally, the same infrastructure can gradually support merchant payments, remittances, government services and eventually more sophisticated financial products.
The country’s fintech ecosystem remains relatively small. Estimates suggest only around 10–20 fintech companies currently operate in The Gambia, concentrated mainly in payments, remittances and basic financial services.
But the infrastructure underneath them is becoming considerably more sophisticated.
The leapfrog is already happening
The numbers reveal the scale of the change.
In six years, The Gambia moved from fewer than one in five people having access to formal financial services to more than four in five.
It did not achieve that transformation by building a conventional banking system on the European model.
Mobile money helped change the route.
Now interoperability could change it again.
The next stage is no longer simply giving Gambians access to digital money.
It is connecting those digital accounts, banks, fintech platforms, merchants and government services into one financial ecosystem.
For one of Africa’s smallest countries, that could make The Gambia an interesting example of something much larger:
how emerging economies can build the financial infrastructure of tomorrow without first building all the infrastructure of yesterday.
Newshub Editorial in Africa – 17 September 2026
Recent Comments