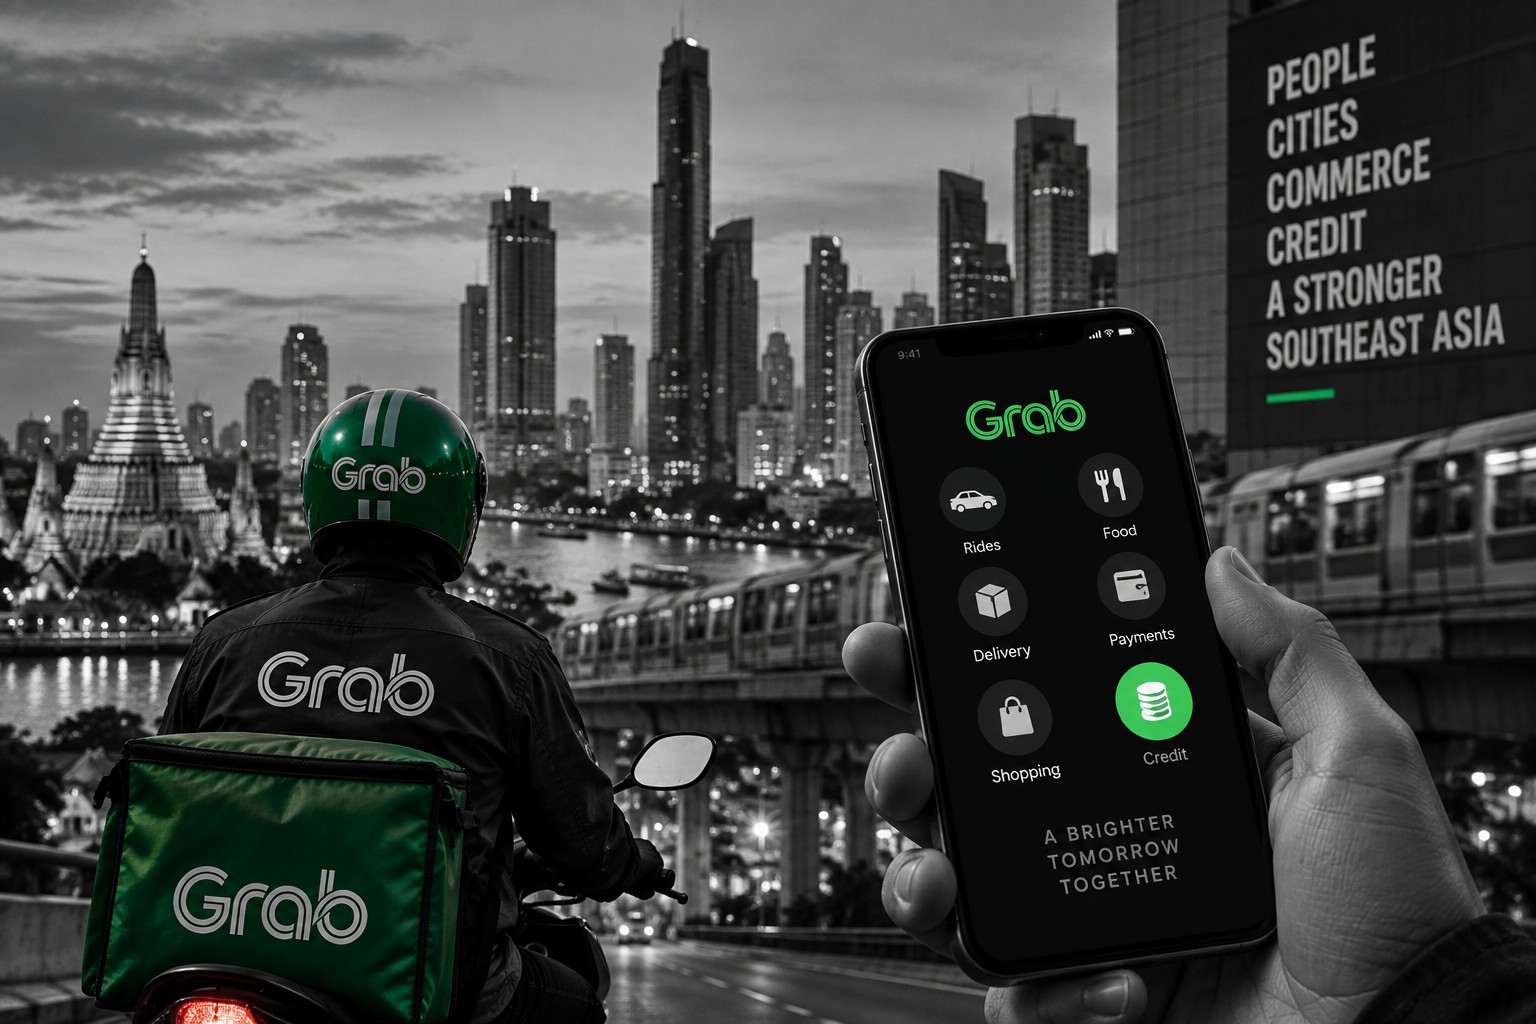
Grab’s $1.49 billion deal for Atome Financial turns Southeast Asia’s superapp race into a battle for consumer finance. What began with rides, deliveries and payments is increasingly becoming something much bigger: a financial ecosystem built around the everyday digital behaviour of millions of people.
A $1.49 billion move into credit
Grab has agreed to acquire 60% of Atome Financial for $1.49 billion in cash, in a deal announced on 15 September.
Atome operates buy-now-pay-later services, cash loans, cards and digital lending across Singapore, Malaysia, the Philippines, Indonesia and Thailand.
The company says it has reached 25 million cumulative transacted users across its five Southeast Asian markets.
But the most important part of the transaction may not be BNPL.
It is what Grab can build around it.
The superapp becomes a financial platform
Grab already sits inside millions of everyday transactions.
A customer orders a ride. Another orders dinner. A merchant receives a payment. Someone buys groceries.
Every interaction creates information about how consumers and businesses behave economically.
By combining that ecosystem with Atome’s credit engine and lending infrastructure, Grab can potentially turn activity into data, data into credit assessment and credit into a much broader financial relationship.
The model is remarkably simple: commerce creates data. Data creates credit. Credit creates a financial ecosystem.
That represents the next stage of the superapp.
The old financial model is being reversed
Traditional banking usually begins with the financial institution.
Bank → account → credit card → loan.
Across emerging Asia, digital platforms increasingly have the opportunity to reverse that sequence.
App → daily activity → payments → data → scoring → credit.
The difference is fundamental.
Grab does not necessarily have to persuade someone to visit a bank, establish a conventional banking relationship and gradually apply for additional financial products.
The customer may already be inside Grab’s ecosystem every day.
Financial services can be placed directly on top of that existing behaviour.
Credit without a traditional credit history
This becomes particularly important in markets where consumers and small businesses may have limited conventional credit histories.
Grab says combining its ecosystem with Atome can improve access to financing for consumers and merchants underserved by traditional credit assessment.
Digital platforms potentially possess something conventional lenders have historically struggled to obtain from such customers: continuous behavioural data.
Payments, purchases and commercial activity can potentially contribute to alternative methods of assessing financial behaviour, subject to regulation, privacy requirements and responsible lending standards.
That could make the superapp itself part of the financial infrastructure.
The numbers reveal Grab’s ambition
Grab’s targets demonstrate how significant financial services could become within the wider group.
The company expects its Financial Services segment, including Atome, to reach approximately $500 million in adjusted EBITDA and more than $6 billion in gross loan portfolio by 2028.
And the initial 60% acquisition may only be the beginning.
Grab has agreed on a mechanism that could allow it to acquire the remaining 40% approximately two years after completion of the first transaction.
That second stage would use a performance-based valuation formula which could value Atome at as much as $4.5 billion.
This is therefore not simply an investment in another fintech company.
It is a substantial bet on credit becoming one of the core layers of Grab’s Southeast Asian ecosystem.
From transactions to relationships
The wider significance extends beyond Grab and Atome.
For years, fintech disruption was largely described as replacing individual banking products: a cheaper payment, a digital wallet, a faster transfer or a better card.
The superapp model potentially changes the competition entirely.
The objective is no longer necessarily to win one financial transaction.
It is to own the digital environment in which the transaction happens.
Mobility brings the customer into the ecosystem. Delivery increases frequency. Merchants create commerce. Payments connect the transactions. Data reveals behaviour. Credit deepens the relationship.
And once savings, insurance, investment and other financial services are added, the distinction between a technology platform and a financial institution becomes increasingly difficult to see.
Southeast Asia’s next fintech battle
This is why Grab’s $1.49 billion Atome deal matters beyond BNPL.
It offers a glimpse of where fintech in emerging Asia may be heading.
The region’s largest digital platforms already have something banks spent generations building: enormous networks of customers and merchants interacting with them every day.
Now they are adding the financial infrastructure.
First came the ride.
Then the food.
Then the payment.
Now comes the money.
Newshub Editorial in Asia – 16 September 2026
Ask NF GPT
If you have an account with ChatGPT you get deeper explanations,
background and context related to what you are reading.
Recent Comments