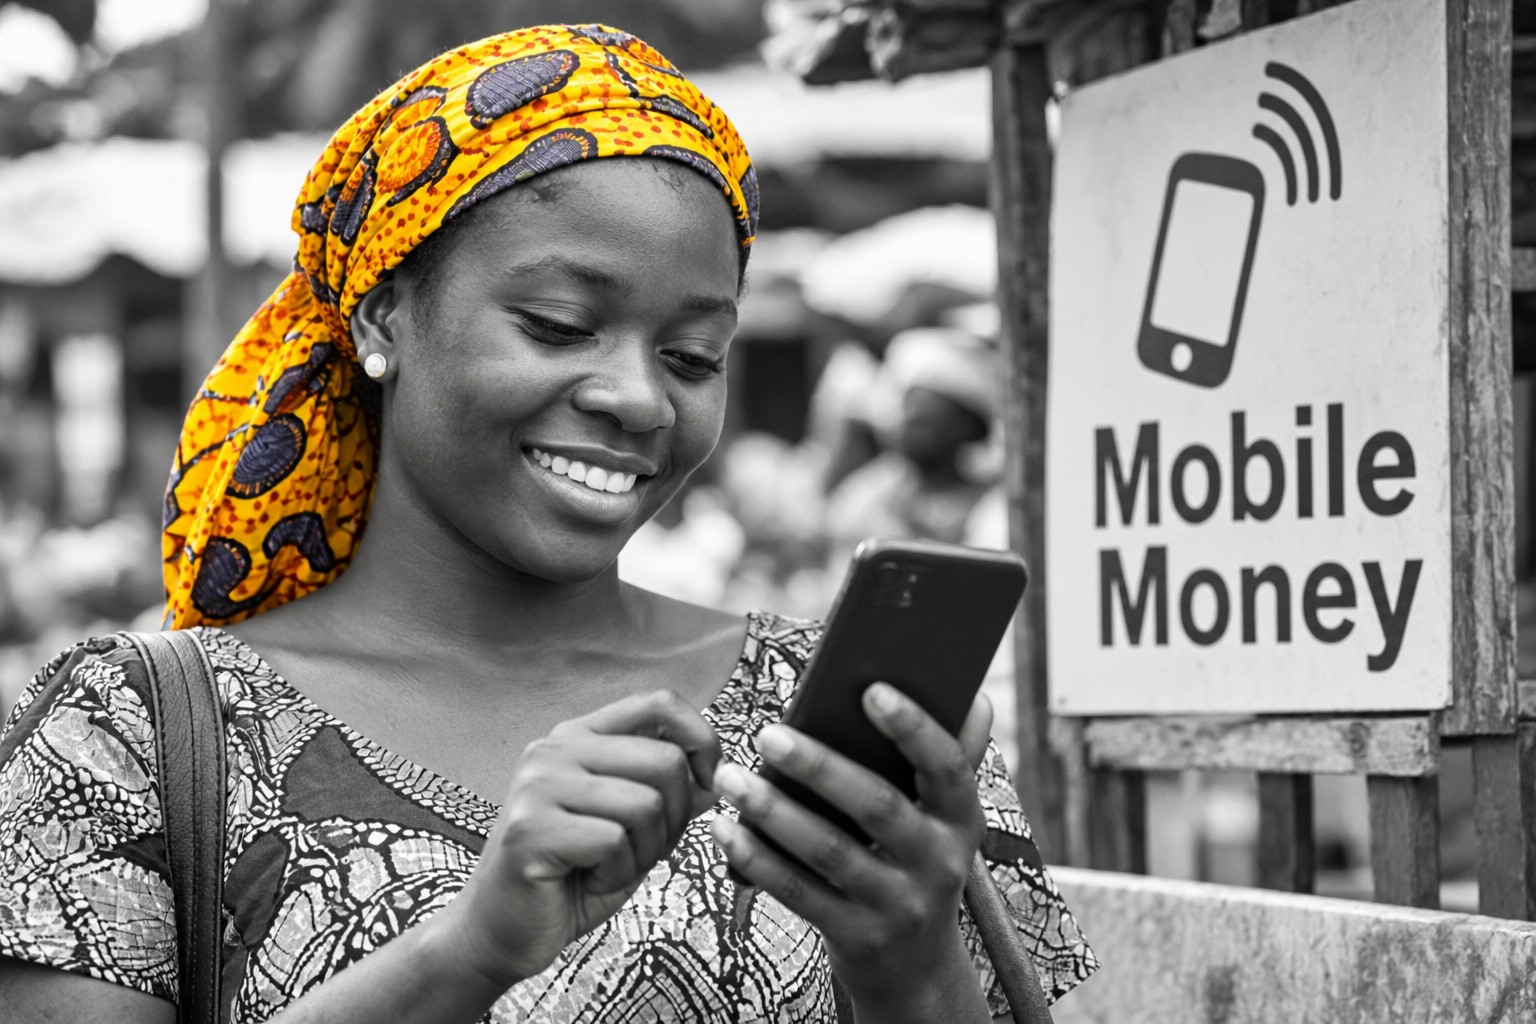
Africa’s rapidly expanding digital economy presents governments with an opportunity to strengthen public finances through improved tax transparency. But the challenge is delicate: identifying taxable digital wealth without discouraging remittances, increasing transaction costs or excluding millions of people who are only beginning to access formal financial services.
A growing digital financial economy Across Africa, mobile money, digital banking and cryptocurrency services are transforming how individuals and businesses manage their finances.
Countries including Kenya, Nigeria, Ghana and South Africa have become important centres of digital financial activity, supported by widespread mobile connectivity and growing demand for affordable financial services.
Yet the expansion of digital transactions does not automatically translate into stronger government revenues.
Some economic activity remains outside traditional reporting systems, while differences in national regulations complicate the identification of taxable income and capital gains.
The opportunity for tax authorities Improved digital reporting could help governments distinguish between ordinary financial transfers and transactions that generate taxable income.
Blockchain analytics, regulated exchanges and cooperation between financial institutions may provide authorities with better information about previously unreported investment profits.
However, transaction volumes should never be confused with taxable wealth. Moving money between personal accounts does not necessarily create income, and unrealised cryptocurrency gains are not automatically taxable.
Effective taxation requires clear legislation, reliable information and appropriate safeguards.
Protecting remittances and financial inclusion Remittances represent an essential financial lifeline for millions of African households.
Money sent by relatives working abroad frequently supports education, healthcare, housing and everyday consumption.
Introducing excessive reporting requirements or additional transaction taxes could encourage people to return to informal transfer networks, reducing transparency rather than improving it.
The same risk applies to mobile money, which has helped bring financial services to communities historically underserved by conventional banks.
A successful tax strategy must therefore protect low-value transfers and ensure that compliance costs remain proportionate.
Transparency without exclusion Governments could prioritise large, demonstrably taxable gains, commercial income and deliberate tax evasion rather than imposing blanket charges on digital transactions.
Simplified reporting, privacy protections and cooperation across borders could improve compliance while preserving access to affordable financial services.
A question of economic balance Africa’s digital economy offers genuine opportunities to broaden the tax base, but the objective should be to tax actual economic gains rather than the movement of money itself.
Greater transparency could strengthen public finances. Poorly designed taxation, however, risks undermining the very financial inclusion that makes digital growth possible.
Newshub Editorial in Africa – 14 October 2026
Africa's rapidly expanding digital economy presents governments with an opportunity to strengthen public finances through improved tax transparency. But the challenge is delicate: identifying taxable digital wealth without discouraging remittances, increasing transaction costs or excluding millions of people who are only beginning to access formal financial services.
Recent Comments