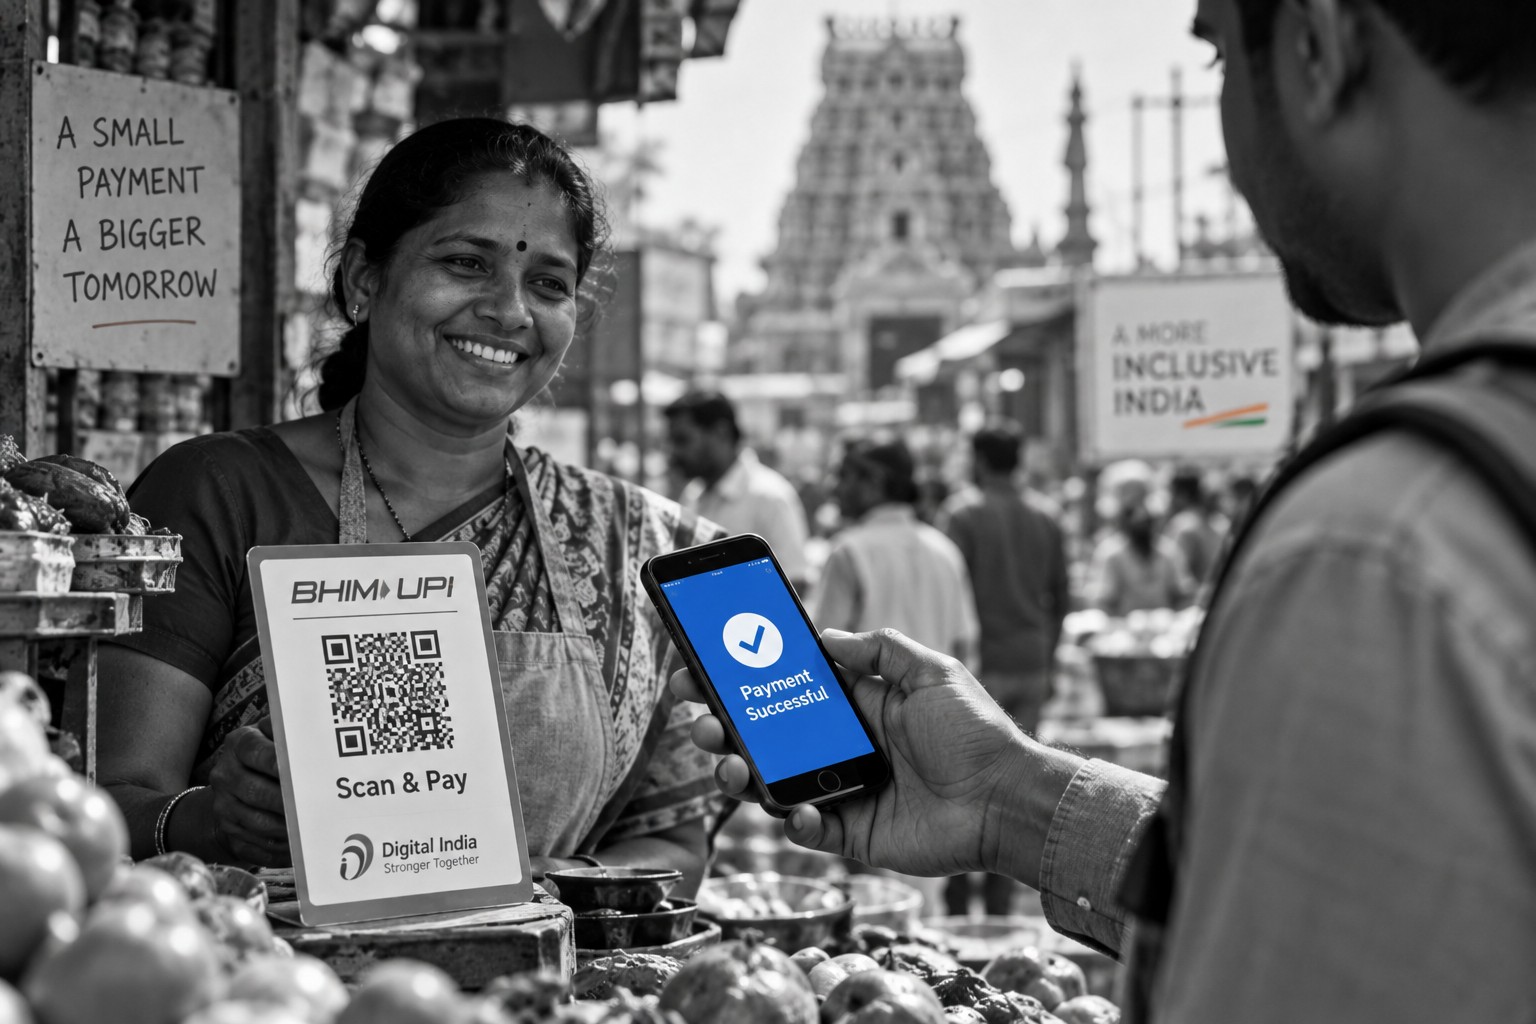
India has postponed the introduction of new charges on larger digital payments, offering temporary relief to millions of merchants ahead of the Diwali shopping season. The decision highlights a growing challenge for emerging economies: how to finance digital payment infrastructure without undermining the affordability that has made financial inclusion possible.
A last-minute decision The National Payments Corporation of India (NPCI) announced on Tuesday, 13 October, that a proposed 0.4% merchant fee on Unified Payments Interface (UPI) transactions exceeding 2,000 rupees would be postponed.
The charge had been scheduled to take effect on 15 October, ending more than six years of zero-cost UPI merchant payments.
Instead, implementation will take place after Diwali, celebrated on 8 November, with a revised date to be announced separately.
More than 500 million users India’s UPI system has become one of the world’s most significant digital payment networks, serving more than 500 million people.
From small street vendors to major retailers, the platform enables instant payments through smartphones, reducing dependence on cash and traditional banking infrastructure.
Companies including PhonePe, Google Pay and Paytm have helped expand access to digital transactions across urban and rural communities.
Its affordability has been central to this growth, particularly among smaller businesses operating with limited margins.
Merchants welcome the postponement The Confederation of All India Traders welcomed the decision, describing the postponement as timely and pragmatic.
Retailers had expressed concerns that introducing transaction charges during the festive shopping season could increase operating costs and disrupt payment habits.
For smaller merchants, even relatively modest fees can become significant when applied across thousands of transactions.
The financial inclusion dilemma The proposed charges expose a broader question facing governments and financial technology companies throughout Asia.
Digital payment systems require continuous investment in security, infrastructure and innovation.
However, transferring those costs directly to merchants risks discouraging adoption, particularly among businesses that have only recently moved away from cash.
Finding a sustainable funding model without excluding low-income consumers remains an important policy challenge.
A model for emerging markets India’s experience offers lessons for countries across Southeast Asia and other emerging markets developing national digital payment networks.
Interoperability, low transaction costs and widespread smartphone access can accelerate financial inclusion, but long-term sustainability requires careful regulation.
The postponed fee remains part of India’s payment policy, leaving the broader debate unresolved.
For now, maintaining affordable digital payments appears to have taken priority over introducing new revenue streams.
Newshub Editorial in Asia – 14 October 2026
India has postponed the introduction of new charges on larger digital payments, offering temporary relief to millions of merchants ahead of the Diwali shopping season. The decision highlights a growing challenge for emerging economies: how to finance digital payment infrastructure without undermining the affordability that has made financial inclusion possible.
Recent Comments