Executive assessment
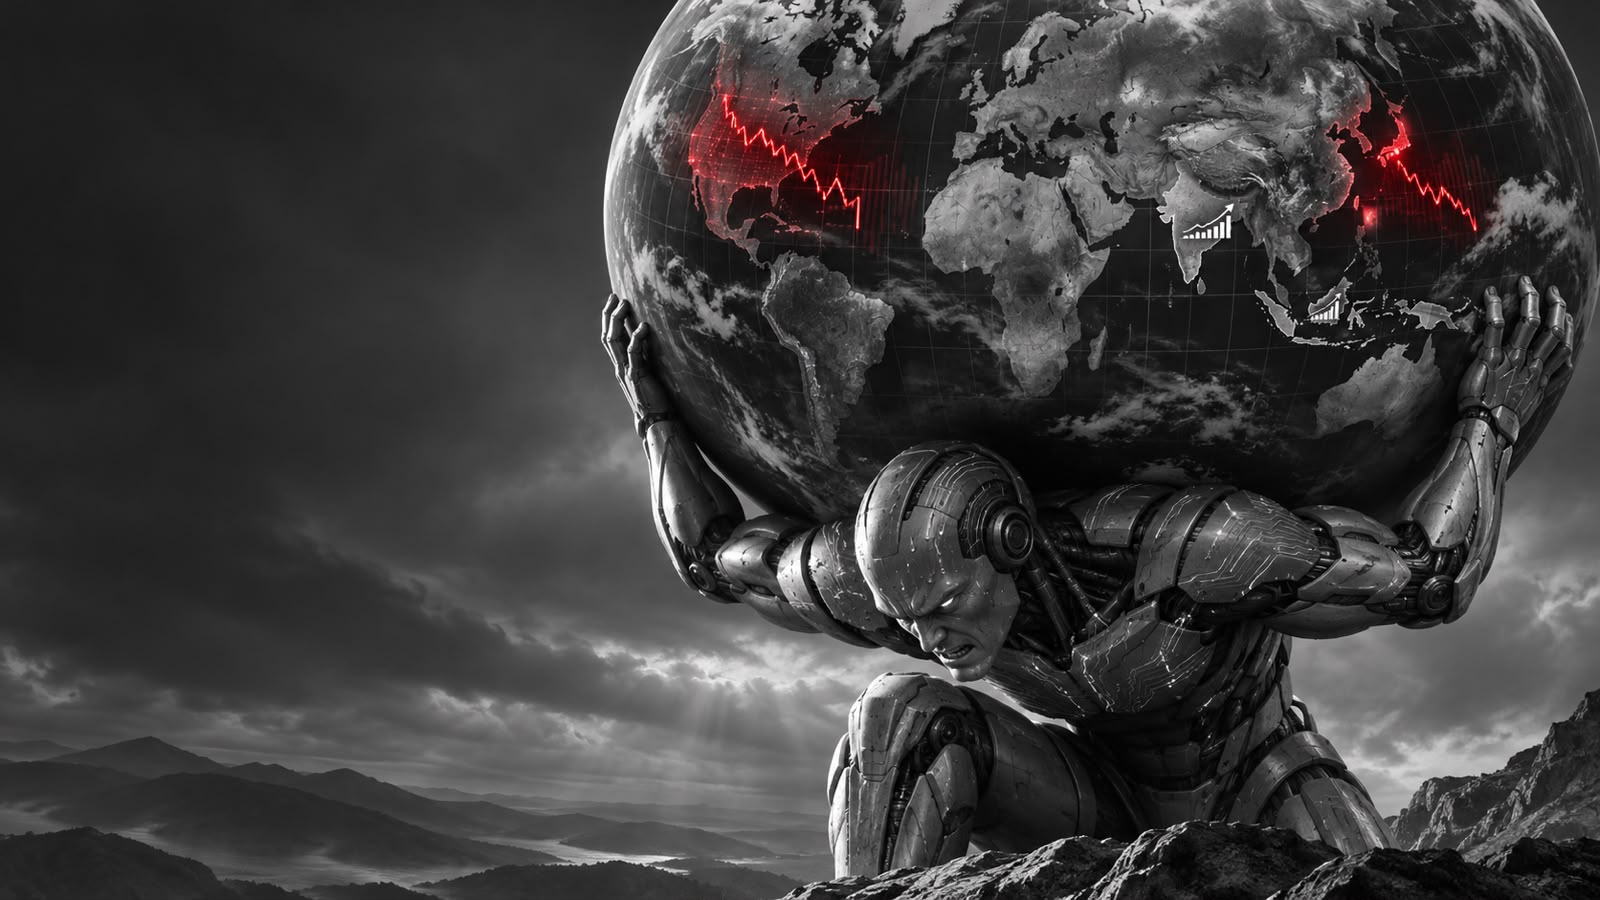
A sharp technology-led sell-off in the United States has spread across Asian markets and into Europe. The immediate trigger appears to be investor concern that the Democrats’ victories in the US midterm elections could lead to greater scrutiny of AI development and data-centre construction.
The election is not the whole explanation. Concerns about exceptionally high AI infrastructure spending, financing costs and the time needed to generate returns were already affecting sentiment. The political news appears to have intensified those concerns and accelerated selling in a market where many investors held similar AI-related positions.
The global pattern is uneven. Japan, South Korea and Taiwan—markets closely tied to semiconductor and AI hardware supply chains—fell sharply. India rose strongly, while Jakarta recovered from an early decline to finish higher. That contrast suggests a concentrated repricing of AI-linked exposure rather than a uniform collapse across global equities.
Ten developments shaping the market
1. Wall Street recorded its steepest decline in more than a year.
On Thursday, 5 November, the Nasdaq Composite fell 5.5%, the S&P 500 dropped 4.4% and the Dow Jones Industrial Average declined 3.4%. The Nasdaq moved into correction territory, more than 10% below its recent record.
2. The midterm results became the immediate political trigger.
Investors began weighing whether a changed balance in Congress could bring tougher federal oversight or support local restrictions on data-centre construction. Those concerns relate to possible future policy and project delays; they do not mean that new restrictions have already stopped the build-out.
3. Asia’s most technology-exposed markets took the biggest hit.
On Friday, Japan’s Nikkei 225 and South Korea’s Kospi each closed down about 6%. Taiwan’s Taiex fell about 4.5%. These markets have substantial exposure to chipmakers and other suppliers serving the global AI build-out.
4. Seoul experienced a sharp intraday shock.
South Korea’s Kospi fell as much as 8.8% before recovering some losses. Trading was briefly halted under the market’s circuit-breaker rules. Samsung Electronics and SK Hynix were among the major companies hit as investors reassessed the outlook for memory chips used in AI systems.
5. Semiconductor shares led the US sell-off.
The Philadelphia Semiconductor Index dropped 12.2% on Thursday. Nvidia fell 9.3% and AMD 17.3%; Qualcomm also declined after disappointing guidance. The breadth of the drop shows how quickly investor concern about future AI infrastructure spending can affect chipmakers and related suppliers.
6. Europe followed Wall Street lower, though its markets are less concentrated in AI stocks.
In early Friday trading, the FTSE 100 was down about 1.5%, Germany’s DAX 1.5%, France’s CAC 40 1.2% and Spain’s IBEX about 1.1%. These are early-session figures, not closing prices. European semiconductor, software and equipment companies were exposed to the same concerns about AI investment.
7. Mumbai moved in the opposite direction.
India’s Nifty 50 and Sensex both rose by more than 2% on Friday, reaching their highest closes in more than eight months. The Nifty gained 8.6% and the Sensex 8.8% over the week—their strongest weekly gains since 2021. Reuters attributed the relative strength to factors including lower oil prices, foreign investment inflows and India’s lower direct exposure to the capital-intensive AI hardware trade.
8. Jakarta also resisted the regional direction by the close.
The Jakarta Composite fell sharply early, touching an intraday low near 4,925, but recovered to close at 5,050.43, up 0.40% on the day. The advance was narrow: local reporting showed more shares fell than rose. So Jakarta finished higher, but the session still reflected significant selling pressure beneath the headline index.
9. Market mechanics intensified the swings.
The VIX volatility index reached an eight-month high. Reuters reported heavy demand for options protection, retail selling and an estimate that leveraged funds might need to sell around $47 billion in shares as they rebalanced. That estimate described potential sales, not a confirmed final total. Such flows can amplify a fall when many investors are reducing similar positions at once.
10. The investment question is about returns—not whether AI exists.
Recent company reports continue to show rapid business growth connected to AI. Alphabet reported 103% year-over-year growth in Google Cloud revenue in its latest quarter, while Microsoft reported 40% growth in Azure and other cloud services and said customer demand continued to exceed available capacity. Those figures support the view that AI demand and infrastructure investment are real. They do not yet establish that every company building or supplying the infrastructure will earn attractive returns on its investment.
Global market snapshot
| Market | Latest reported move | Session status at report time |
|---|---|---|
| United States | Nasdaq −5.5%; S&P 500 −4.4%; Dow −3.4% | Thursday close; Friday trading had not yet begun |
| Japan | Nikkei 225 about −6.0% | Friday close |
| South Korea | Kospi about −6.0% | Friday close, after a much steeper intraday fall |
| Taiwan | Taiex about −4.5% | Friday close |
| Mainland China | Shanghai about −1.2%; Shenzhen about −2.4% | Friday close |
| Hong Kong | Hang Seng about −1.0% | Friday close |
| India | Nifty 50 and Sensex each up more than 2% | Friday close |
| Indonesia | Jakarta Composite +0.40% to 5,050.43 | Friday close; recovered from an early fall |
| Australia | S&P/ASX 200 about −0.5% | Friday close |
| Europe | Major indices down roughly 1–1.5% | Early Friday trading; not closing figures |
Regional figures are reported from different market sessions and timestamps. The US numbers are Thursday’s closing moves; Asia, India, Indonesia and Australia had closed Friday; European figures are early-session reports.
NHX assessment
The midterm election results appear to have supplied the immediate spark. The deeper fuel was already present: uncertainty over AI investment returns, high infrastructure costs, financing needs and the possibility that data-centre construction could face delays or local resistance.
The divergence between Seoul and Tokyo on one side, and Mumbai and Jakarta on the other, is significant. The sell-off has been most severe in markets and companies directly tied to the AI hardware cycle. Markets with less direct exposure have shown more resilience, although their performance may also reflect local conditions such as energy prices and investment flows.
The underlying AI expansion remains powerful. Customer demand, cloud growth and infrastructure spending are visible in company results. The market is now asking whether the profits generated by that growth will justify the scale and cost of the build-out.
NHX’s early conclusion: this is a severe global repricing of AI-related risk, triggered by political uncertainty and amplified by crowded positioning and market mechanics. It is not yet evidence that AI demand or development has stopped. The key test will be whether investment continues to translate into revenue, cash flow and durable returns.
This is an early market assessment, not investment advice. European figures were still intraday at the report’s cut-off; market prices and policy expectations can change quickly.
Executive assessment A sharp technology-led sell-off in the United States has spread across Asian markets and into Europe. The immediate trigger appears to be investor concern that the Democrats’ victories in the US midterm elections could lead to greater scrutiny of AI development and data-centre construction.
Recent Comments