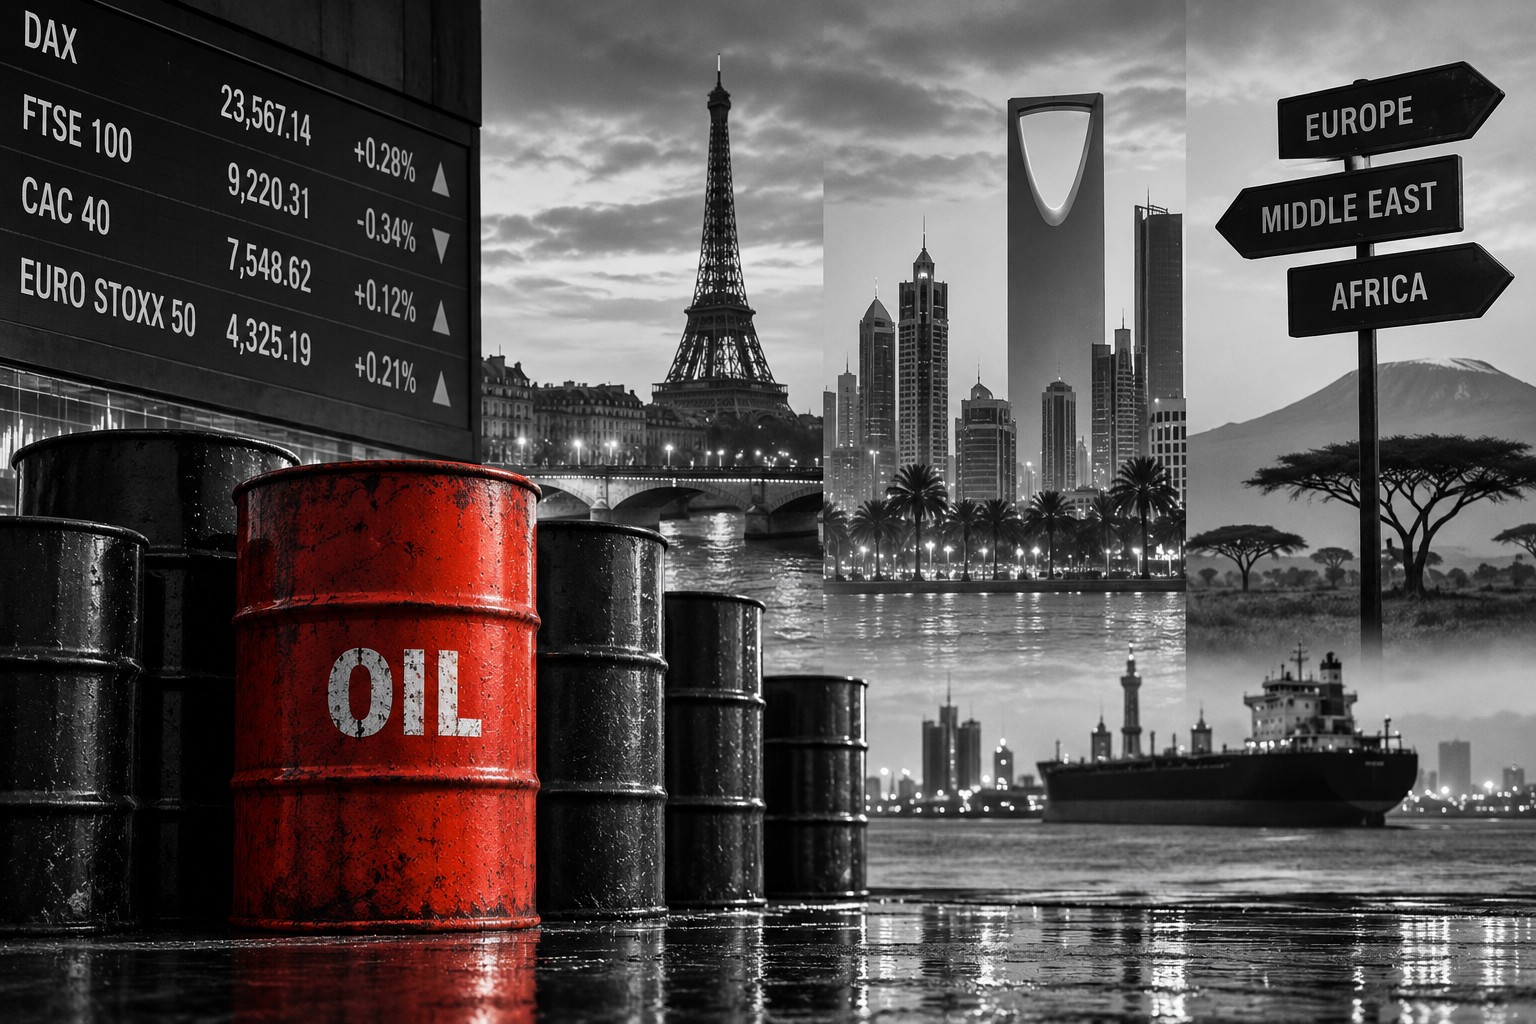
Markets across Europe, Africa and the Arab world opened Tuesday with investors confronting a rapidly changing global risk environment. Oil above $107 a barrel, US Treasury yields exceeding 5% and renewed attacks on Saudi energy infrastructure are reshaping expectations for inflation and interest rates — but the reaction across regional equity markets has been far from uniform.
Europe opens cautiously
European markets began Tuesday with little appetite for aggressive risk-taking.
The Euro Stoxx 50 opened close to unchanged, while Germany’s DAX was also broadly flat. London showed greater weakness, with the FTSE 100 initially under pressure.
The cautious opening followed another sharp move in global bond markets. The US 10-year Treasury yield climbed above 5.02%, its highest level since 2007, while Japanese government bond yields also reached multi-decade highs.
Higher yields increase financing costs and can reduce the relative attractiveness of equities, particularly highly valued growth and technology companies.
For Europe, however, another problem is becoming increasingly difficult to ignore: energy.
Oil returns as Europe’s problem
Brent crude climbed approximately 1.7% in early European trading to around $107.50 a barrel, while US WTI moved above $103.
The rise follows attacks on Saudi Arabia’s East-West pipeline and continuing concerns surrounding shipping through the Strait of Hormuz.
Europe remains highly exposed to international energy prices. Sustained crude above $100 could feed back into transport, manufacturing and consumer prices just as policymakers had hoped inflationary pressure was becoming more manageable.
That creates an uncomfortable combination for markets: slower growth accompanied by renewed inflation.
Arab markets face the crisis at home
For Arab markets, the situation is different.
Higher oil prices can strengthen revenues for major Gulf exporters, but the reason behind the latest increase is itself a source of market risk.
Saudi Arabia has faced attacks against energy infrastructure, while security concerns around shipping routes have intensified. The country’s East-West pipeline is particularly important because it allows crude to reach the Red Sea without passing through the Strait of Hormuz.
Saudi Arabia’s Tadawul had entered Tuesday after gaining 0.13% on Monday to 10,878.46.
Elsewhere in the Gulf, Dubai had risen around 0.6% in the previous session, while Abu Dhabi finished marginally higher.
Investors are therefore facing two opposing forces.
Expensive oil improves the economic position of major energy exporters. But attacks on infrastructure and threats to shipping increase geopolitical risk and can rapidly outweigh the benefits of higher crude prices.
Africa shows surprising strength
African markets presented a more varied picture Tuesday morning.
South Africa’s JSE was showing strong gains in early trading, with the broader market around 1.8% higher according to live continental market data.
Morocco was also advancing, by around 0.7%, while Egypt’s market had recovered approximately 0.8% after suffering significant losses during Monday’s session.
Nigeria and Ghana were slightly weaker.
The moves demonstrate why Africa cannot be treated as a single market.
Oil exporters can potentially benefit from higher energy prices, while import-dependent economies face increased pressure on inflation, currencies and trade balances.
South Africa is particularly exposed because it imports significant quantities of oil. The rand had already weakened on Monday as crude prices climbed.
Egypt attempts a recovery
Egypt’s market deserves particular attention after Monday’s sharp decline.
The benchmark EGX30 fell 1.56% on Monday, while the broader EGX100 dropped 2.3%. Approximately EGP 65 billion was erased from total market capitalisation during the session.
Tuesday’s early recovery therefore represents at least a partial reversal of that pressure rather than an entirely new trend.
As elsewhere across emerging markets, the direction of the dollar and US interest rates will remain critical.
The Fed now matters everywhere
Behind the regional movements lies one global question: what happens to interest rates?
Markets are pricing a high probability that the US Federal Reserve will raise rates by 25 basis points this week as policymakers confront renewed inflation pressure.
That matters far beyond Wall Street.
Higher US rates can strengthen the dollar, increase borrowing costs and pull international capital towards dollar-denominated assets.
For emerging economies across Africa and the Arab world, that can mean greater pressure on currencies and government financing.
For Europe, it complicates the outlook for growth and monetary policy.
Tuesday’s opening therefore reveals an increasingly interconnected market.
An attack on an oil pipeline in Saudi Arabia pushes crude above $107.
Higher oil raises inflation expectations.
Inflation pushes bond yields higher.
Higher yields change expectations for central banks.
And those expectations move equities from Frankfurt and London to Johannesburg, Cairo and Dubai.
The geography may be different.
The risk is increasingly global.
Newshub Editorial in Europe, Africa and the Middle East – 15 September 2026
Ask NF GPT
If you have an account with ChatGPT you get deeper explanations,
background and context related to what you are reading.
Recent Comments