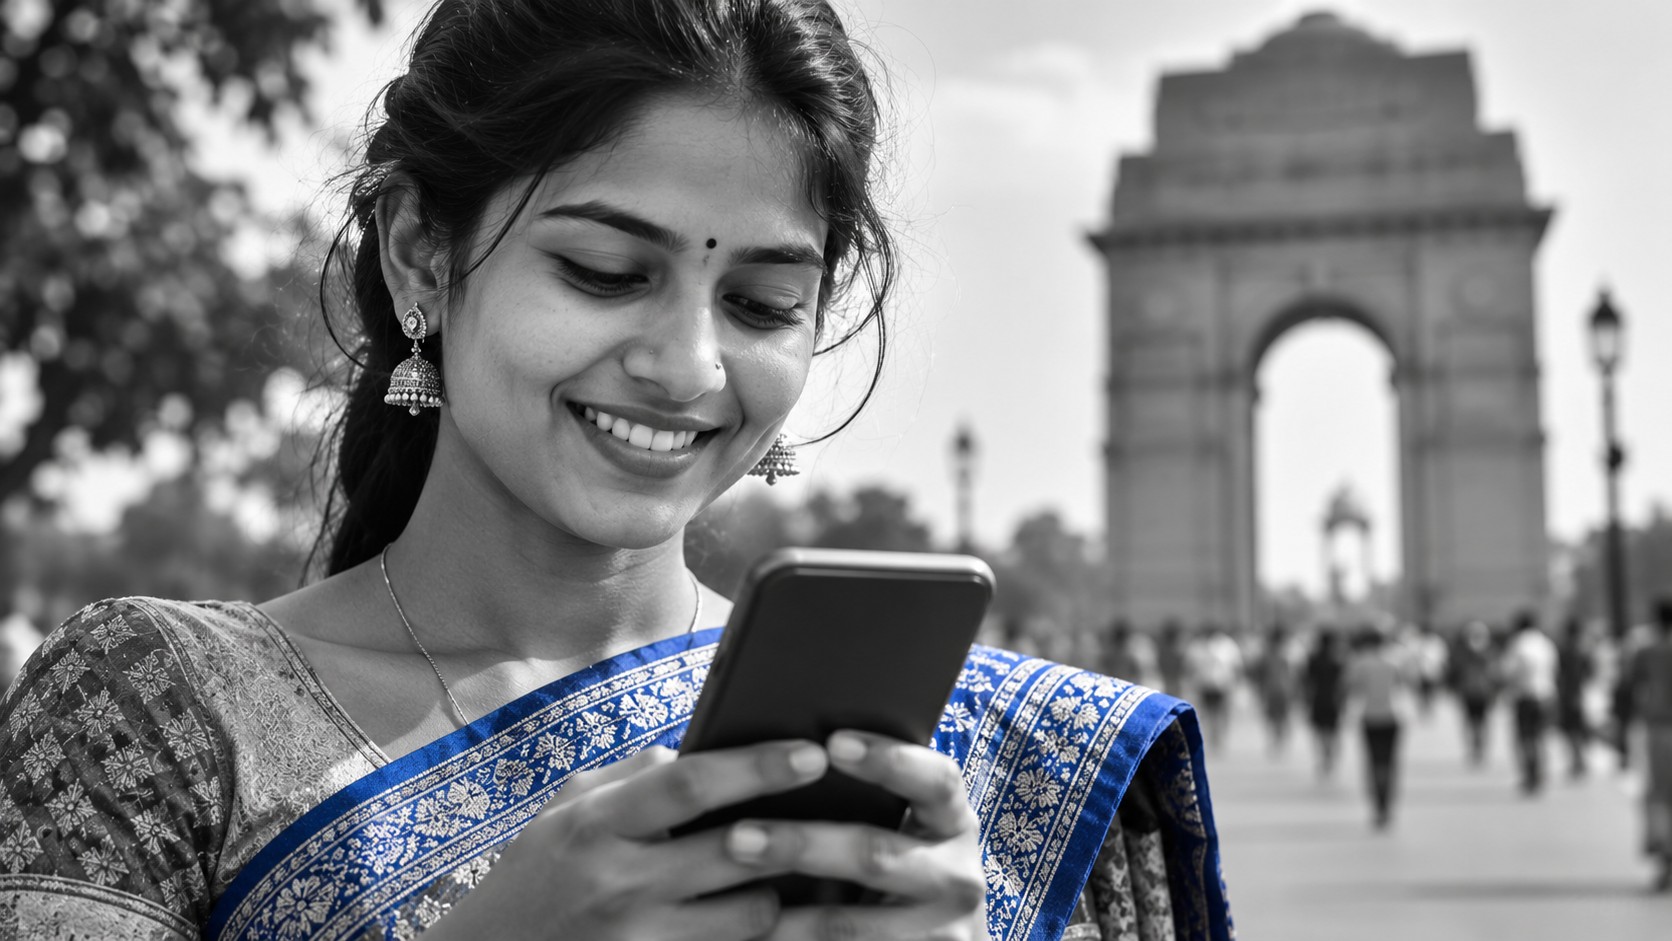
India is strengthening its position as a global leader in financial inclusion, with nearly 600 million basic bank accounts and record-breaking digital payment volumes transforming access to financial services. New figures from the Reserve Bank of India and government institutions show that the country’s financial infrastructure is expanding beyond traditional banking, creating opportunities for rural communities, women, small businesses and previously underserved populations.
Nearly 600 million accounts demonstrate rapid expansion
India’s Pradhan Mantri Jan Dhan Yojana (PMJDY), launched in 2014, has become one of the world’s largest financial inclusion programmes.
By 28 October 2026, approximately 596.7 million accounts had been opened under the initiative, with deposits reaching ₹3.22 trillion.
Women held approximately 333 million accounts, representing more than half of the total. Around 463 million accounts were registered through rural and semi-urban banking branches.
The programme provides basic banking facilities and supports access to government payments, savings products, insurance and other financial services.
Digital payments transform everyday transactions
India’s Unified Payments Interface (UPI) has become a central component of the country’s digital economy.
During October 2026, UPI processed approximately 25.47 billion transactions, with a combined value exceeding ₹31.5 trillion.
The system enables individuals and businesses to transfer money instantly using smartphones, reducing dependence on cash and conventional banking infrastructure.
For small retailers, agricultural businesses and informal traders, digital payments can improve transaction records and create opportunities to access formal credit.
Financial inclusion index reaches new high
The Reserve Bank of India’s Financial Inclusion Index increased to 70.0 in March 2026, compared with 67.0 a year earlier.
The improvement was primarily driven by greater usage of financial services rather than simply increasing the number of bank accounts.
This distinction is important. Financial inclusion requires more than account ownership. Customers must also be able to save securely, receive payments, obtain appropriate credit and protect themselves against financial risks.
Challenges remain in rural communities
Despite considerable progress, India continues to face obstacles involving digital literacy, smartphone accessibility, internet connectivity and financial education.
Women, agricultural workers and low-income households can encounter additional barriers when accessing credit, insurance and digital banking services.
The Reserve Bank’s National Strategy for Financial Inclusion 2025–2030 places increased emphasis on effective financial participation, consumer protection and improving access for underserved groups.
A model for emerging economies
India’s combination of digital identity, basic bank accounts, instant payments and government-backed financial programmes offers important lessons for other emerging markets.
For financial technology companies and microfinance institutions, the country’s experience demonstrates how accessible digital infrastructure can support broader economic participation.
As India moves towards 2030, the central challenge will be ensuring that financial services are not only available to millions of additional people, but also affordable, secure and genuinely useful in their everyday lives.
NewsHub Finance | Financial Inclusion | 7 November 2026
India is strengthening its position as a global leader in financial inclusion, with nearly 600 million basic bank accounts and record-breaking digital payment volumes transforming access to financial services. New figures from the Reserve Bank of India and government institutions show that the country's financial infrastructure is expanding beyond traditional banking, creating opportunities for rural communities, women, small businesses and previously underserved populations.
Recent Comments