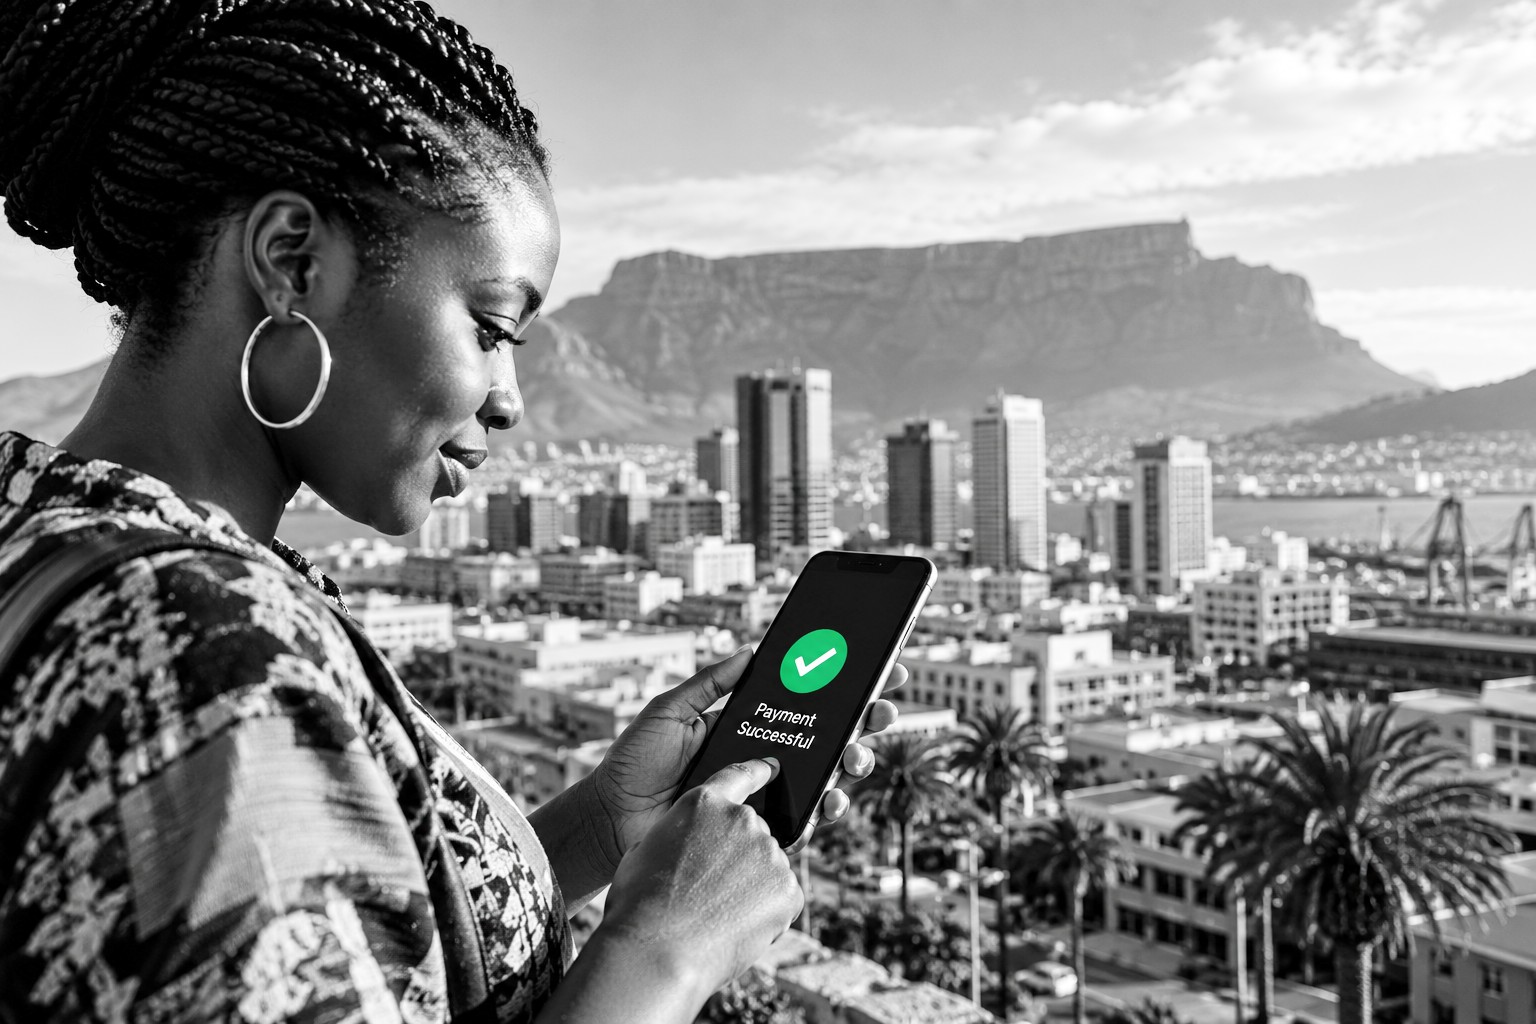
JOHANNESBURG — South Africa is preparing one of its most significant financial reforms in decades, opening its national payment infrastructure to fintech companies, telecommunications operators and retailers. The move could challenge the dominance of traditional banks, reduce transaction costs and accelerate financial inclusion across Africa’s most industrialised economy.
The South African Reserve Bank (SARB) announced that non-bank financial service providers will be allowed to participate directly in the country’s payment system from 2027.
The reform forms part of the central bank’s Payments Ecosystem Modernisation programme, designed to create a more competitive and accessible digital financial sector.
Breaking the banks’ traditional dominance
South Africa’s national payment infrastructure has historically been controlled largely by licensed banks, requiring fintech companies and other payment providers to work through established financial institutions.
The planned changes would allow qualifying non-bank companies to access payment infrastructure more directly, subject to regulatory approval and operational requirements.
New rules and licensing details are expected by November 2026, with the first non-bank participants scheduled to begin operating in March 2027 following testing.
For fintech businesses, direct participation could reduce dependence on banking intermediaries and provide greater flexibility in developing payment services.
Faster payments and wider financial inclusion
A central objective is to expand access to affordable financial services, particularly among lower-income consumers, informal businesses and communities underserved by conventional banking.
The Reserve Bank is also working to strengthen PayShap, South Africa’s real-time payment platform, alongside improvements in digital identity verification and payment security.
Lower transaction costs could benefit small merchants that currently rely heavily on cash or expensive electronic payment services.
The reforms could also encourage innovation in mobile wallets, merchant payments and other financial technology applications.
Cash remains part of the strategy
Despite the emphasis on digital payments, South African authorities recognise that cash remains essential for millions of consumers.
The central bank is therefore considering a national cash utility to improve distribution efficiency and reduce the cost of handling physical currency.
A network of shared, white-label ATMs is also planned, with pilot operations expected in January 2027 and a broader rollout by the end of that year.
A potential model for African fintech
South Africa’s initiative reflects a wider transformation of African financial infrastructure, where regulators increasingly seek to combine innovation with consumer protection and financial stability.
Opening payment systems could create opportunities for smaller fintech providers while increasing competitive pressure on established banks.
However, successful implementation will depend on clear licensing standards, cybersecurity safeguards and fair access to infrastructure.
If the reforms deliver their intended results, South Africa could establish an important precedent for more open, competitive and inclusive payment systems across the continent.
NewsHub Finance | Africa, Fintech & Financial Inclusion | 20 October 2026
JOHANNESBURG — South Africa is preparing one of its most significant financial reforms in decades, opening its national payment infrastructure to fintech companies, telecommunications operators and retailers. The move could challenge the dominance of traditional banks, reduce transaction costs and accelerate financial inclusion across Africa's most industrialised economy.
Recent Comments