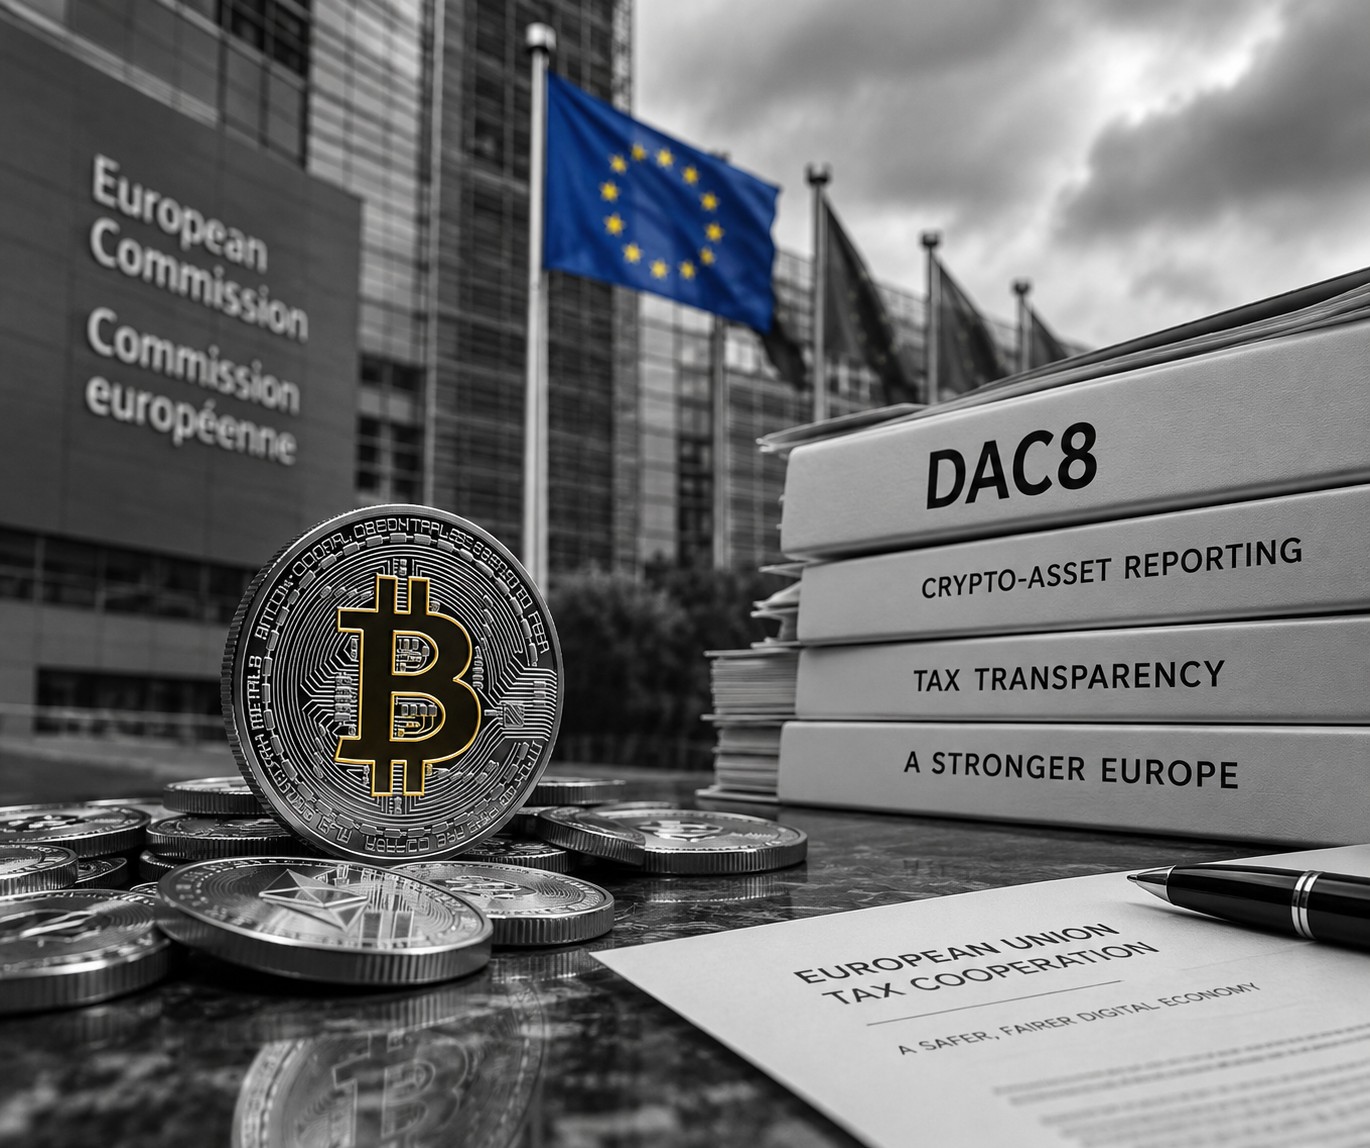
Europe is preparing one of the most significant changes to cryptocurrency taxation since Bitcoin was created. Under the European Union’s DAC8 directive, crypto-asset service providers will face new reporting obligations, giving tax authorities unprecedented access to information about digital transactions. With reporting beginning in 2026 and the first international exchanges scheduled for 2027, the era of largely fragmented crypto-tax information is approaching a turning point.
A new chapter in financial transparency
For more than a decade, cryptocurrency investors have operated in a financial environment where national tax authorities often struggled to obtain reliable information about cross-border transactions.
Bitcoin, Ethereum and thousands of other digital assets could be traded through platforms operating outside an investor’s home country, complicating the identification of taxable gains.
The European Union intends to reduce that information gap.
DAC8, the eighth amendment to the Directive on Administrative Cooperation, extends existing tax-information exchange arrangements to crypto-assets.
Rather than introducing a new cryptocurrency tax, the legislation creates a reporting infrastructure designed to help authorities enforce existing national tax rules.
What exchanges must report
Under DAC8, reporting crypto-asset service providers must collect information identifying relevant customers and their tax residence.
The reporting also covers aggregated transaction values, purchases, disposals and certain transfers, including transactions involving stablecoins and other qualifying digital assets.
The information will be supplied to national tax administrations and exchanged with other EU countries where relevant.
Importantly, the system does not automatically reveal every historical blockchain transaction or establish whether a taxpayer has underpaid tax. It provides authorities with additional information that can be compared with tax declarations.
Why 2027 matters
The reporting rules became applicable on 1 January 2026.
Throughout 2026, covered providers must collect relevant information. The first reporting and international exchange cycle will follow in 2027, with exchanges between EU tax authorities due by 30 September.
This creates an important opportunity for authorities to identify discrepancies between declared cryptocurrency income and information received from exchanges.
However, the actual amount of additional tax revenue remains uncertain.
A global reporting network emerges
Europe’s initiative is part of a wider international transformation.
The Organisation for Economic Co-operation and Development has developed the Crypto-Asset Reporting Framework, known as CARF, to facilitate automatic information exchange between participating jurisdictions.
DAC8 incorporates this international approach into European legislation.
As more countries implement compatible systems, transferring crypto-assets across borders may become less effective as a means of avoiding tax scrutiny.
The beginning of a new era
For investors, the implications are significant. Accurate transaction histories, acquisition costs and tax declarations will become increasingly important.
For governments, the challenge will be converting new information into effective enforcement while protecting taxpayers’ rights and personal data.
The cryptocurrency market is not becoming fully transparent overnight. Decentralised transactions and incomplete historical records will continue to present difficulties.
But 2027 could mark a fundamental shift: the moment when systematic international reporting begins to replace fragmented national oversight of digital assets.
NewsHub Finance | Global Economy & Digital Finance | 15 October 2026
Europe is preparing one of the most significant changes to cryptocurrency taxation since Bitcoin was created. Under the European Union’s DAC8 directive, crypto-asset service providers will face new reporting obligations, giving tax authorities unprecedented access to information about digital transactions. With reporting beginning in 2026 and the first international exchanges scheduled for 2027, the era of largely fragmented crypto-tax information is approaching a turning point.
Recent Comments