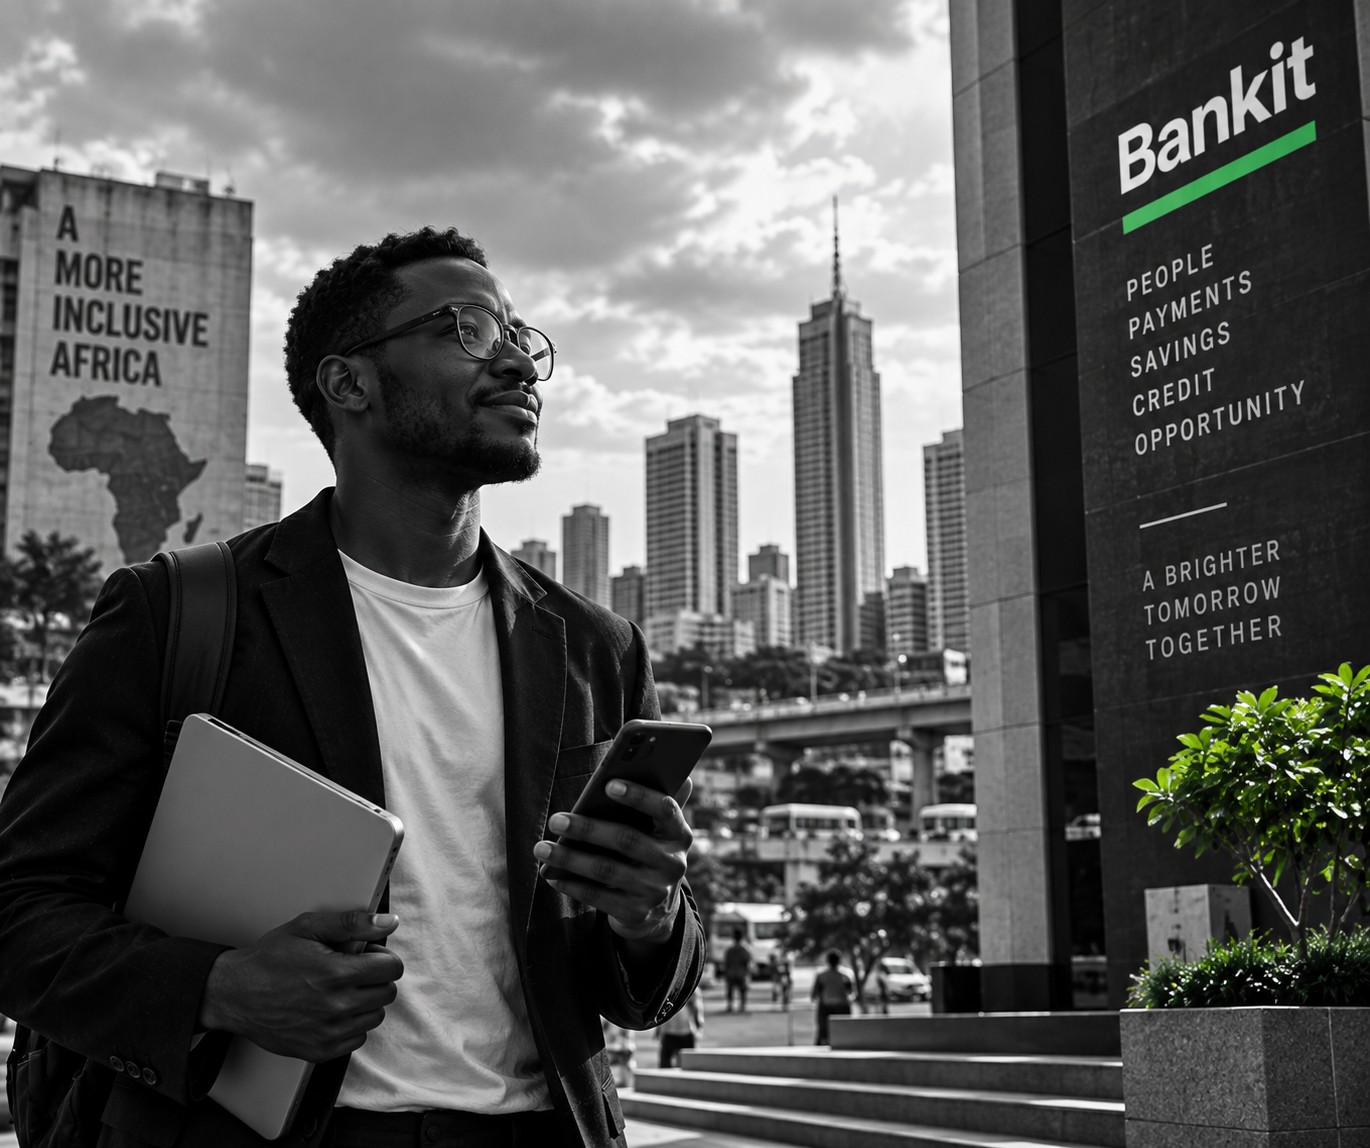
Nigerian fintech Bankit has launched a new digital banking platform, expanding from its origins as a payment aggregator into direct financial services for consumers and businesses. The move reflects a wider transformation taking place across African finance, where technology companies are increasingly building banking services around mobile-first customers.
From payments to banking
Bankit announced the transition on 18 September, broadening its business beyond processing payments to provide a wider range of digital financial services.
The strategy is particularly relevant in Nigeria, where mobile technology and fintech platforms have created alternative routes into the financial system for consumers and businesses that may previously have depended on cash or limited conventional banking infrastructure.
Rather than requiring customers to begin their relationship with a physical bank branch, digital platforms can put accounts, transfers, payments and other financial services directly onto a mobile device.
Nigeria becomes a digital banking laboratory
Nigeria has developed one of Africa’s most active fintech ecosystems. Competition now extends across banks, mobile-money operators, payment companies and technology-led financial platforms.
Bankit’s move illustrates how the boundaries between those categories are becoming increasingly blurred. A company can begin by solving one problem, such as payments, and then use its technology and customer relationships to build a broader financial ecosystem.
The development comes as Nigeria is also tightening the rules surrounding its financial infrastructure. The Central Bank of Nigeria has introduced requirements for payment data to be stored locally, adding another dimension to the country’s rapidly evolving digital-finance market.
A wider African transformation
Bankit is not alone. African fintech companies are increasingly moving deeper into banking and cross-border finance.
Nigerian business-focused digital bank Nomba recently secured a $3 million debt facility to expand payment infrastructure linking Africa with Asia. The company reportedly processes more than $480 million in cross-border payments each month.
Meanwhile, Ericsson says roughly 70–75% of the 131 million users on its global fintech platform are in Africa, demonstrating the scale at which mobile financial infrastructure has developed across the continent.
The bank moves into the phone
The significance of Bankit’s expansion is therefore larger than another fintech product launch.
Emerging markets do not necessarily need to reproduce the branch-heavy banking systems developed over generations in Europe and North America. Smartphones, digital identity, payment networks and alternative financial data provide another route.
For millions of consumers and small businesses, the mobile device can effectively become the bank branch.
Bankit’s transition from payments company to digital banking platform is another example of that model taking shape — and of Nigeria’s growing role in defining how the next generation of African banking could operate.
Newshub Editorial in Africa – 20 September 2026
Ask NF GPT
If you have an account with ChatGPT you get deeper explanations,
background and context related to what you are reading.
Recent Comments